Private equity firms in Southeast Asia are increasingly turning away from traditional auction processes to secure exits, with fund managers saying sellers must cultivate buyers directly and be willing to consider bilateral and more creative transactions.
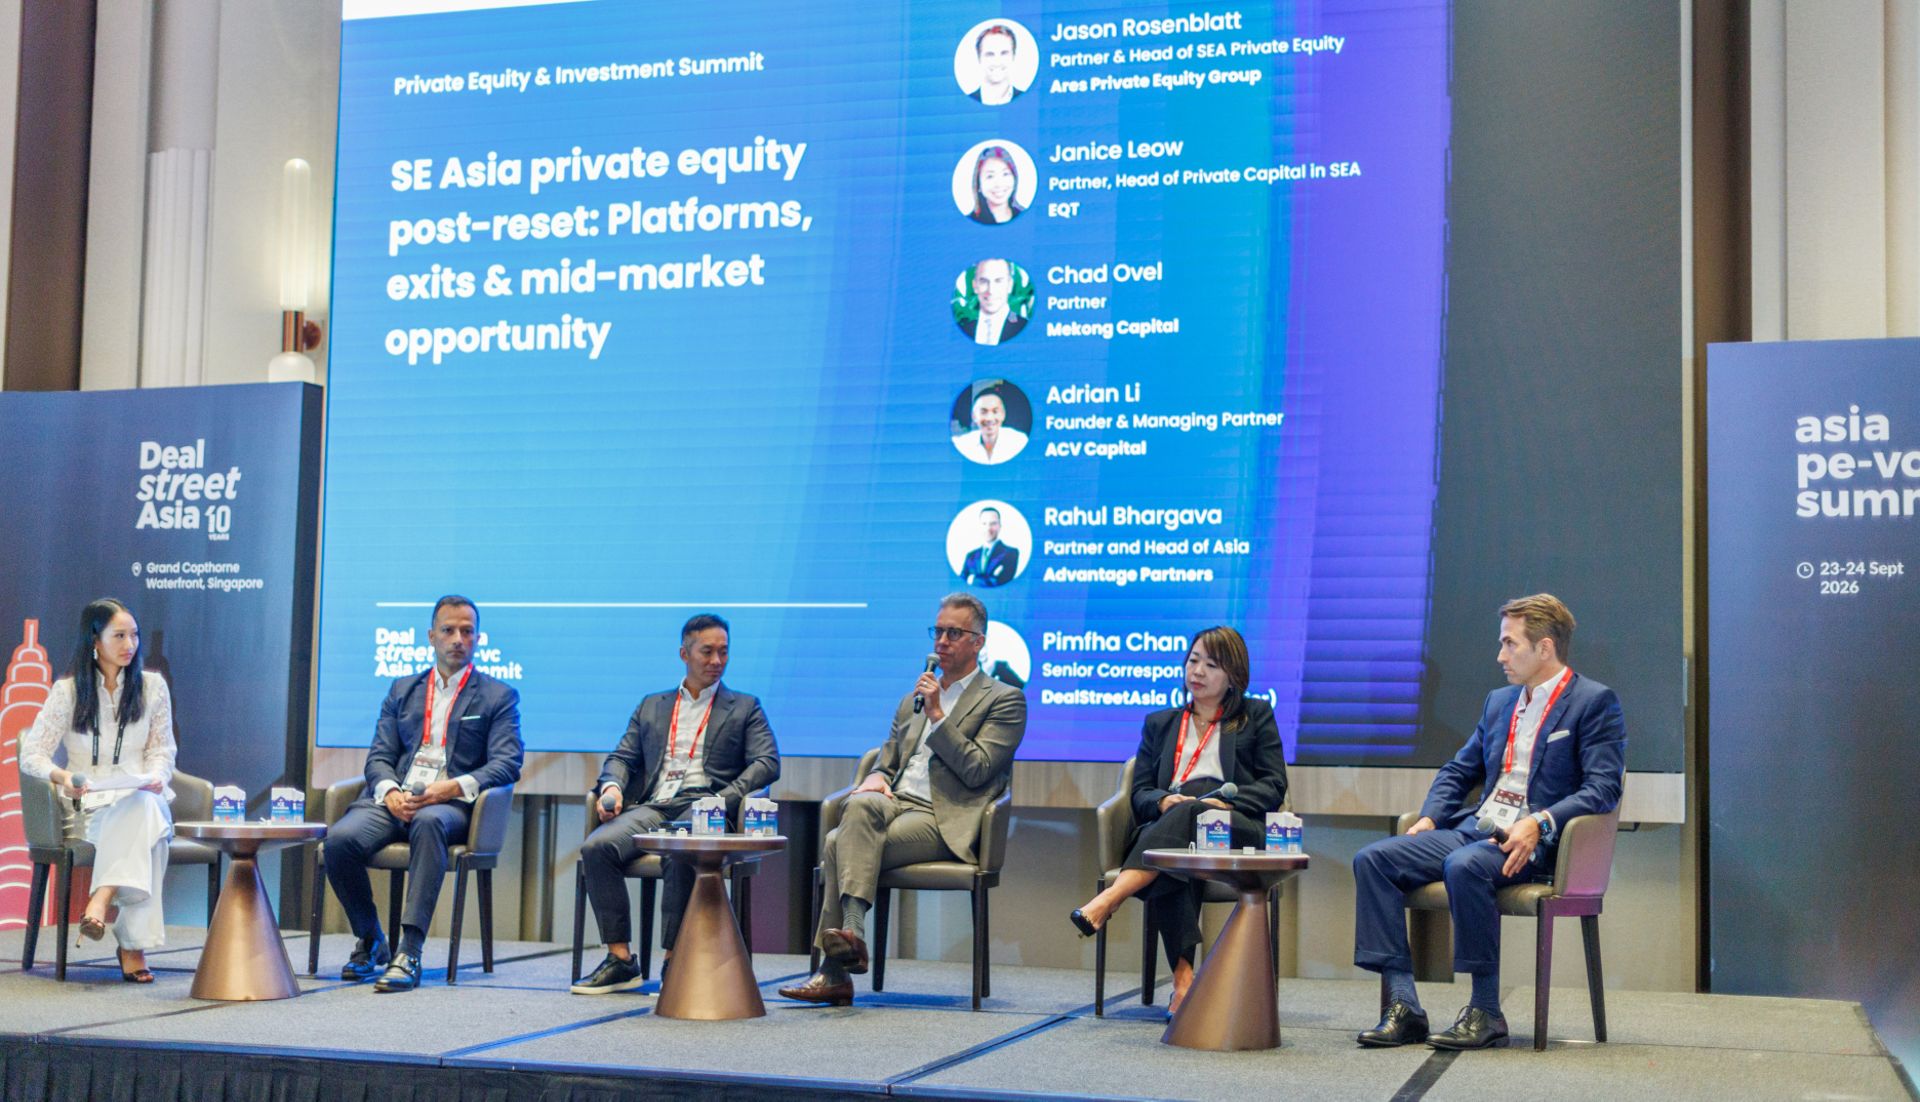
“The old tested route of hiring an investment banker, running a process, and picking the highest bidder—that has not been working for us,” said Chad Ovel, a partner at Mekong Capital, during a panel discussion on September 23 at the Asia PE-VC Summit 2026. His firm has instead relied on its own networks to approach wealthy families, strategic buyers in Vietnam and potential buyers elsewhere in the region.
Mekong exited its majority stake in water purification maker Mutosi Group to European water solutions group Ariston after investing $10 million in Mutosi via its Enterprise Fund IV in 2021.
The traditional auction process was proving less effective at this point in the cycle, with many deals having remained on the market for some time as buyers and sellers struggled to agree on valuations, echoed Janice Leow, EQT’s head of private capital in Southeast Asia during the panel discussion titled ‘SE Asia private equity post-reset: Platforms, exits & mid-market opportunity‘.
“You’ll see activity pick up as some of these sellers reduce their expectations, but a lot of them don’t want to run this kind of process in order to get the exit done,” Leow said. “Sellers like us, whilst we continue to run some of these auctions, are increasingly open to bilateral approaches from many parties, particularly for assets that have been on our books for some time, and we’re really open to creative structures.”
“This is not the time to use the same playbook that used to exist three years ago. It’s really time to be creative,” she added.
The shift reflects a growing imbalance between the supply of assets seeking exits and the amount of capital available to buy them. Private equity fundraising in Asia averaged about $280 billion a year between 2018 and 2022, before falling to roughly $110 billion from 2023 to 2025, with about $66 billion in 2025, according to Jason Rosenblatt, Ares Private Equity Group’s head of SEA.
That has left a large pool of assets for sale, making traditional broad auctions harder to execute. “It’s not the easiest time to be a seller. You can’t just hire a bank and expect strategics and private equity firms to come through the door, and that is partially because the market has changed,” he said. Sellers increasingly need to cultivate potential buyers before launching a process and maintain a degree of competition between a smaller group of parties, he added.
The sale process of Blackstone’s Interplex Datacom reached a binding agreement in about six months after the firm appointed a financial advisor to carve out part of its portfolio. Similarly, Dymon’s Meiban was rolled over to its new fund after the private equity investor invited bidders to put in an offer. CVC’s minority stakes in Fast Group were eventually sold back to the founding family this year after running a sale process in 2025.
Still, the constrained exit market is not deterring asset owners from coming to market, particularly as more family-owned businesses reach succession points and become open to outside capital, according to Adrian Li, founder and managing partner of ACV Capital.
Despite the tighter funding environment, the supply of potential deals remains plentiful, particularly among smaller, family-owned businesses, according to Li. “This entire region is filled with a long tail of mid-market companies that are profitable, family-owned, and have been built over the years and haven’t traditionally taken outside capital in the past,” he said.
That is creating opportunities for private equity firms, but also requires more preparation from sellers, including identifying potential strategic buyers and developing an equity story around the asset.
That means sponsors need to think about the eventual buyer well before an exit, according to Rahul Bhargava, Partner and Head of Asia at Advantage Partners. The firm builds businesses with strategic buyers in mind, particularly across industrial, manufacturing and business-to-business services, and spends time identifying potential acquirers and developing an equity story around areas such as market entry, new capabilities and acquisition pipelines.
“The key [for M&A exit] is really asset selection, building it in a way that is downside protected for the acquirer, particularly the Japanese acquirers who are a lot more focused on making sure the company doesn’t blow up under their their ownership, and building an equity story for them,” said Bhargava. “If it’s just a straight bolt-on where you haven’t done your work around the equity story, as others have pointed out, just hiring a banker and running a process won’t work in this market.”
The shift toward more targeted and bespoke processes comes as Southeast Asia’s exit market begins to show signs of recovery after several subdued years. Fund managers on the panel said they were seeing more processes get underway in the second half of the year, although transactions are still taking longer to close as buyers conduct more diligence and work through conditions precedent.
That points to a market where exit activity is returning, but where sponsors can no longer rely on a conventional auction to deliver liquidity. Instead, managers are increasingly having to identify buyers early, shape assets for specific strategic interests and remain flexible on transaction structures as they look to return capital to investors.