Global limited partners (LPs) risk missing out on a historic wave of technological innovation as China reaches near parity with the US in key areas, including artificial intelligence (AI). Yet, global capital remains under-allocated to its booming tech market.
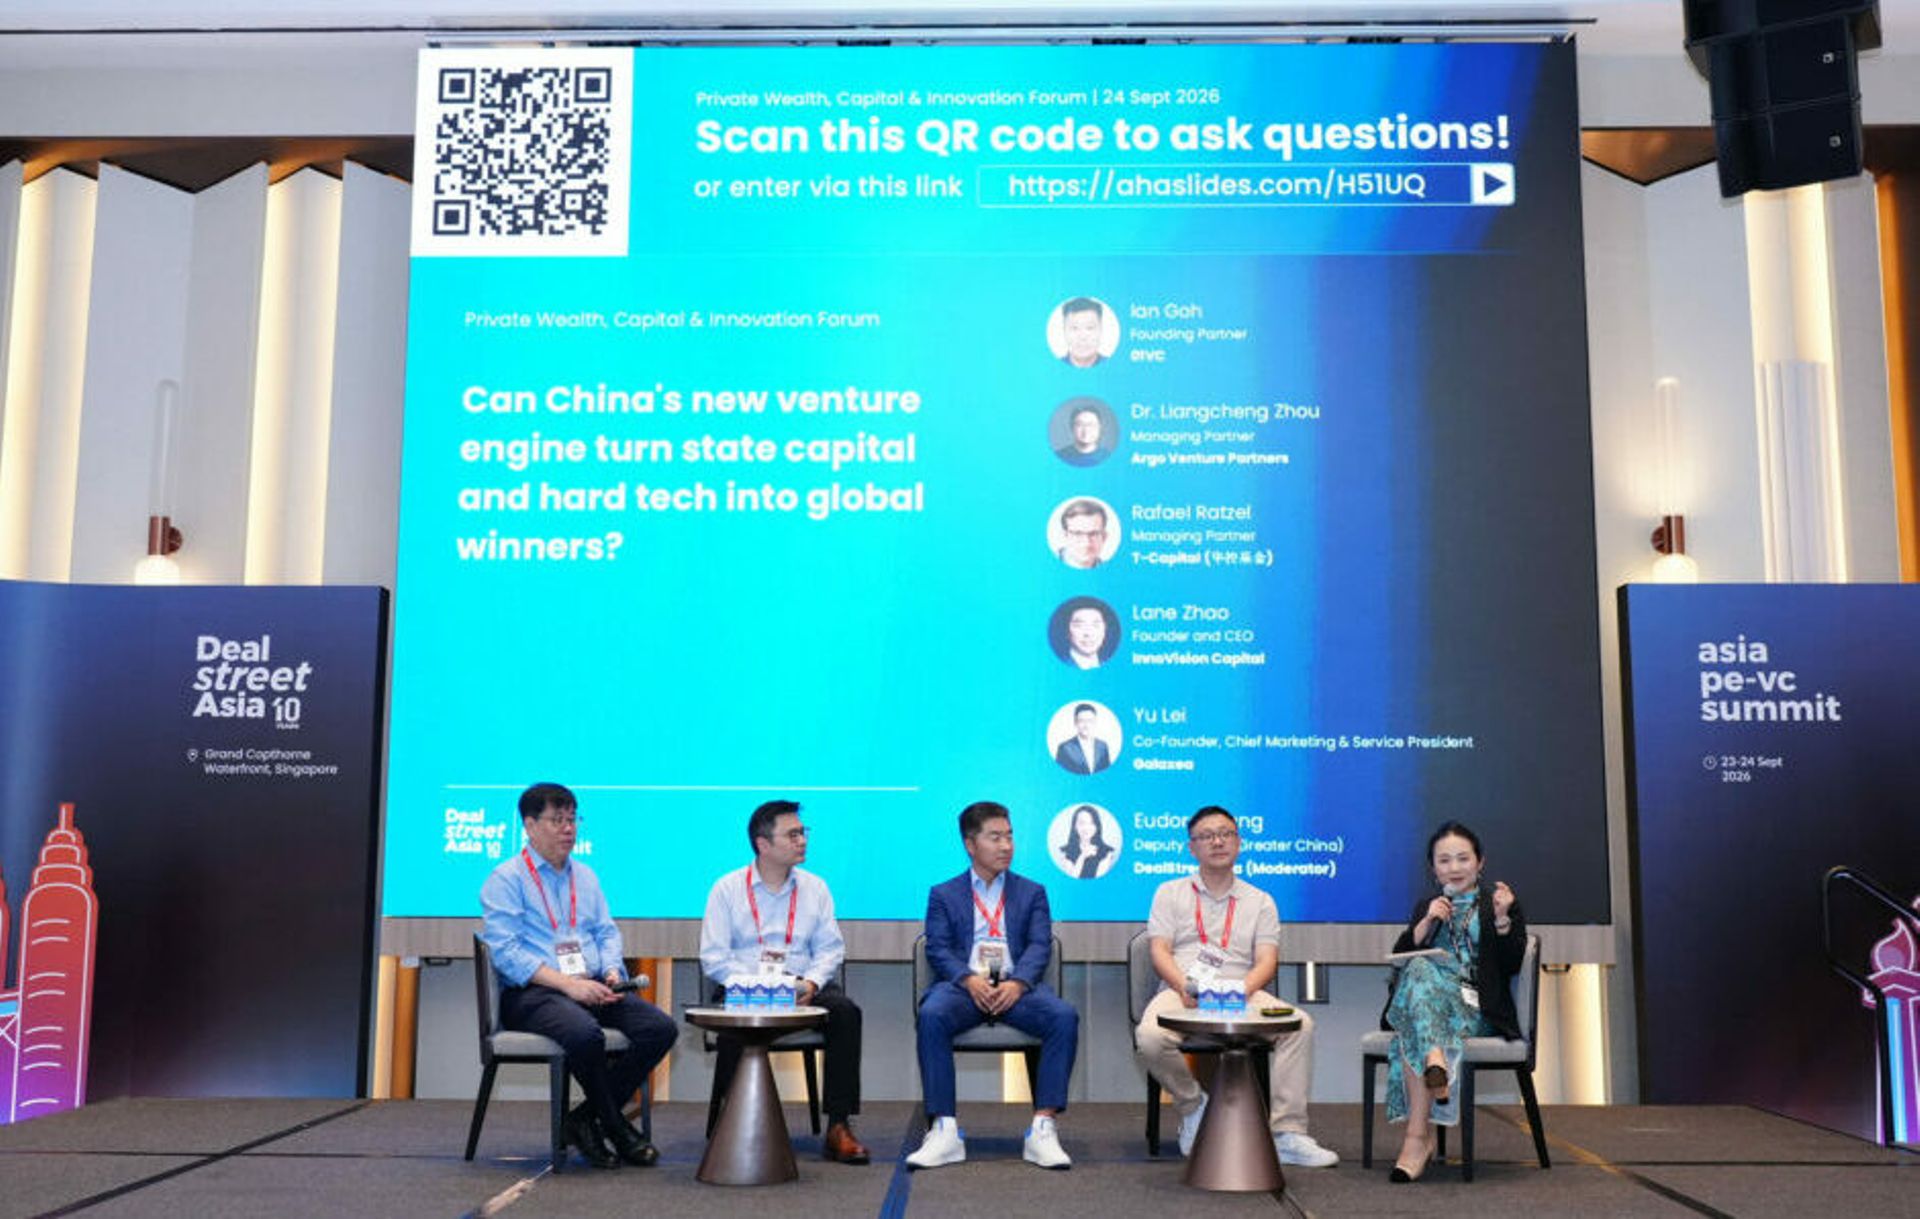
Speaking at DealStreetAsia’s Asia PE-VC Summit 2026 in Singapore, China-focused fund managers called for global institutional investors to increase their LP allocations to the world’s second-biggest economy, which has emerged as a global powerhouse in deep tech. However, much of the global capital today is missing the boat.
“A lot of US dollar LPs have reduced their exposure to China to something like 15%-20% of their Asian allocation, which amounts to just single digits out of their global capital allocation,” said Lane Zhao, founder and CEO of InnoVision Capital, during a panel discussion.
“But if you truly want to allocate the right amount of capital to the AI industry to capture that opportunity over your lifetime, back-of-the-envelope, how much capital should you allocate to China? But unfortunately, it’s not happening anytime soon – hopefully soon, but not now at least,” said Zhao.
With Chinese open-weight models surging in global popularity and the US-China AI performance gap effectively closing, China’s private markets are witnessing a funding boom across AI and embodied intelligence – or AI integrated into physical bodies like robots and autonomous vehicles, allowing it to perceive, learn, and interact directly with the real world.
AI fundraising in China has demonstrated exponential growth this year. In the first six months of 2026, the overall funding into Chinese AI startups reached $12.7 billion, outperforming H1 2025 by 11.3x and representing a 3.6x increase even compared to last year’s total, according to proprietary data from DealStreetAsia’s report, Greater China Deal Review: Q2 2026.
Following AI, embodied intelligence came second, with 217 deals raising more than $9.8 billion in H1 2026, the report shows. The two core AI sectors, alongside health tech & biotech, semiconductor, clean tech, and space tech, account for the bulk of China’s private market opportunities. Collectively, they contributed to 77.4% of deal value and 69.6% of deal volume in H1.
However, this fundraising surge for deep tech startups in China is largely powered by domestic sovereign and private capital investing in Chinese yuan. Global investors remain cautious and highly selective. Foreign currencies, predominantly US dollars, only made up an estimated 29% of H1’s capital deployment in China’s private markets, according to Chinese data intelligence firm Zero2IPO Research.
As Chinese high-flying AI leaders including DeepSeek and MoonShot AI accelerate their paths to public markets at unprecedented speeds and San Francisco-based Anthropic targets an initial public offering (IPO) this November, Zhao of InnoVision Capital warned that the prime window for private market investors to capture global AI lab champions has passed.
What is coming next, he said, is a massive expansion around two AI-centric areas, namely AI infrastructure, including high-performance GPUs and CPUs, silicon photonics, optical modules, and 3D semiconductor memory stacking; and AI applications, such as physical AI world models and consumer/enterprise-focused AI agents.
Beyond AI, other compelling deep tech investment opportunities are also taking shape in China, including quantum computing. “It will probably take another five to 10 years for quantum computing to reach that inflection point and commercialise. But once it passes that inflection point, the space will become much more competitive than all of today’s AI infrastructure,” said Zhao.
Exits from USD-backed Chinese tech assets: Unpredictable?
Despite these opportunities, many global LPs find their hands tied. Institutional capital continues to view China with hesitation due to ongoing geopolitical and regulatory constraints and shorter exit windows.
For foreign LPs, a paramount concern leading to this persistent wait-and-see attitude towards investing in China is exit. Market participants frequently point to regulatory risks and complex cross-border compliance as major obstacles to realising returns from their China tech portfolios.
Despite cases like Beijing’s veto of the $2-billion Meta-Manus deal, fund managers operating on the ground dismissed the notion that exits from Chinese tech assets are “unpredictable” or “government controlled.”
To navigate the complicated exit terrain, Dr. Liangcheng Zhou, managing partner of Argo Venture Partners, said that it is important for founders to clarify their target markets from day one and build from where their customers are.
While certain non-sensitive tech hardware companies can remain in China for supply chain advantages and domestic IPO plans, USD-funded, globally focused Chinese tech startups should consider relocating to regions like the US or Singapore for compliance and ecosystem proximity, said Dr. Zhou, a Silicon Valley-based venture capitalist.
Although purely domestic tech opportunities are largely reserved for onshore investors, companies focused on global commercialisation would design their corporate structures and compliance frameworks to enable access to international capital markets.
For seasoned global tech investors, exits from USD-backed tech companies growing out of China are completely feasible, said Dr. Zhou. He framed it quite bluntly: “If you think exits from Chinese tech assets are unpredictable due to regulatory concerns, you are probably not in the game.”
InnoVision Capital’s Zhao, who characterised China’s exit conditions as “cyclical,” detailed multiple exit routes for Chinese tech assets beyond traditional IPOs.
“M&A will increasingly be a very important exit path,” said Zhao, noting active efforts from the China Securities Regulatory Commission (CSRC) in encouraging mergers and acquisitions (M&A) involving Chinese listed companies to leverage the large cash piles sitting for years on their balance sheets.
General partner (GP)-led secondaries are also becoming more viable, Zhao added. “For exits, we need to be disciplined, take multiple approaches, and manage different market or policy cycles across geographies.”
But that is not to say all will emerge as winners in this AI supercycle. Recent secondary market corrections – such as the July sell-off in China’s public markets that wiped out roughly 10 trillion yuan ($1.5 trillion) over two weeks – were heavily concentrated in high-growth tech sectors.
While panellists view this pullback as a routine reality check rather than a threat to Chinese tech’s core fundamentals, Dr. Zhou noted that, like every prior tech cycle, the majority of today’s 300 or so Chinese embodied intelligence startups will fail, leaving only 20 to 30 winners.
That, he explained, is natural in a “game of concentration.” Investors like himself are waiting to see which companies can demonstrate the “scaling laws” of AI applications and unit economics that deliver clear return on investment (ROI) for clients.
The new “going global” playbook
Geopolitical headwinds and dual-currency dynamics mean that not all Chinese tech assets are accessible to global investors. However, non-sensitive emerging tech with global ambitions still offers rich investment opportunities.
“We’re talking about entrepreneurs who are advancing consumer tech globally, trying to be the next Anker, Dreame, or Roborock. These people are able and willing to take US dollar funds because they are not so ‘being loved’ by RMB funds,” said Ian Goh, founding partner of 01VC.
RMB funding nowadays is heavily focused on policy-driven sectors, including AI, embodied intelligence, semiconductors, and space tech. Despite the dominance of RMB in China’s venture market, USD capital remains crucial for Chinese going-global consumer hardware startups, as well as players across other emerging tech industries, such as B2B payment platforms using stablecoins, Goh explained.
Beyond corporate structures and compliance, the operational realities of taking homegrown tech abroad present a steep learning curve for Chinese founders.
As Goh observed, China no longer lacks engineering talent, capital, or tech execution. “The challenge for a lot of startups going global is how to bring those tech, manufacturing, and cost advantages to a global audience,” he said. Moving from domestic market dominance to international adoption requires navigating a few key hurdles, including global client validation, deep localisation, and client-centric economics.
In the world of embodied intelligence, where Chinese players are rapidly progressing from lab research to global commercialisation, Beijing-based Galaxea is advancing its “outcome-based” Robotics-as-a-Service (RaaS) commercial model to explore how physical AI products can cover expanding labour demands across global markets where labour is increasingly scarce and expensive.
Yu Lei, Galaxea’s co-founder, chief marketing and service president, revealed that the company is in talks with Singapore’s Changi Airport, which is building its Terminal 5 (T5), a massive 1,080-hectare site in Changi East designed to match the land area of all four existing terminals combined.
As the Changi Airport T5 is scheduled to open in the mid-2030s, labour is one of the major challenges, said Yu. Galaxea is seeking opportunities to deploy its full-stack embodied AI foundation models and hardware systems into the new terminal for tasks like luggage handling, cleaning, and retail services.
Under the RaaS model, Galaxea’s commercial roadmap has shifted from one-time upfront hardware sales to a flexible, subscription-based operational expenditure (OpEx) framework. By bundling hardware leasing, continuous software updates, cloud maintenance, and deployment support, it lowers entry barriers for commercial and industrial clients.
In turn, placing its humanoid and mobile robots into active workstations allows Galaxea to charge clients based on real productivity gains while capturing closed-loop physical data to continually refine its foundation models.
“I think the best way to commercialise is to grow with our customers and solve these problems together,” said Yu. To turn this homegrown Chinese embodied intelligence unicorn into a global success, Yu believes it requires a mindset open to sharing China’s supply chain, manufacturing, talent, and capital gains.
“We are a China-funded company, so most of the funds that we’ve raised are from China, including both US dollar funds and some state capital. But if we want to do business in the global market, we need to attract more global investors and global partners.”