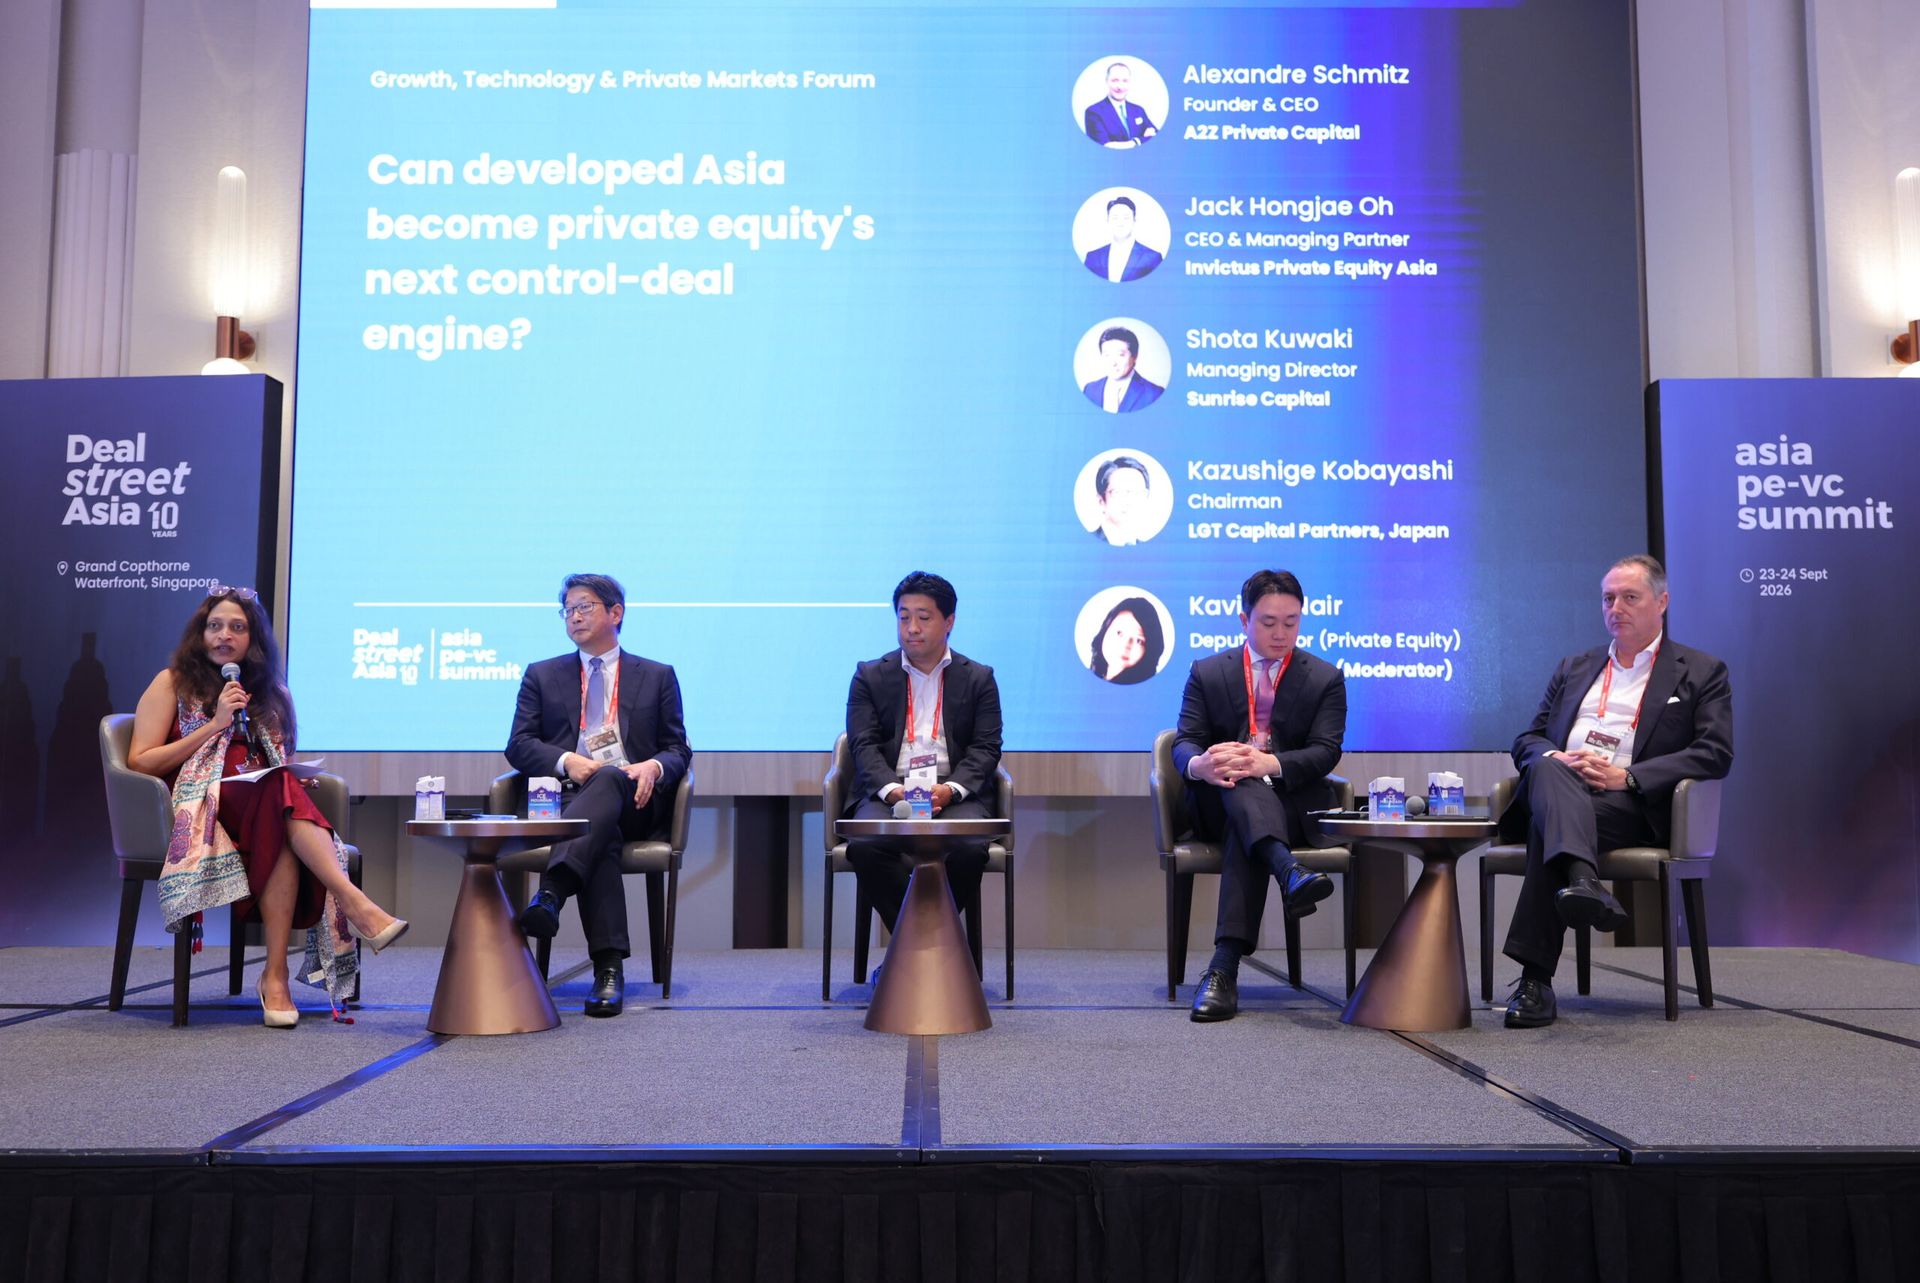
Developed Asian markets are on course to become private equity’s next control-deal engine thanks to robust deal supply and market-specific tailwinds. In Japan, succession sales, governance reform and corporate carve-outs are producing assets while, in Korea, conglomerate restructuring and founder succession are doing the same. And selling to a buyout fund is no longer a last resort for owners.
“Historically, Japanese buyout firms were referred to as vulture funds,” said Shota Kuwaki, Managing Director of Sunrise Capital, at the Asia PE-VC Summit 2026, held in Singapore recently. “Selling to a private equity sponsor used to be opportunistic. Now it is a valid option among the selling options.”
In Korea, Jack Hongjae Oh, CEO and Managing Partner of Invictus Private Equity Asia, pointed to an active deal flow across carve-outs, mid-cap family-owned groups and succession. “Succession is the hottest issue for small-cap deals,” he said.
They were joined by other panellists Alexandre Schmitz, Founder and CEO of A2Z Private Capital, and Kazushige Kobayashi, Chairman of LGT Capital Partners Japan, to explore the potential of developed Asia.
Kuwaki touched upon opportunities created by Japan’s market structure. “We think Japan is good right now because it isn’t so big,” he said. “That’s why we still find a lot of inefficiencies, which is where we can create a lot of value.”
When asked what could hold the market back, some pointed to competition, others to the market’s size. Oh said strategic buyers in Korea were becoming formidable rivals as competition turns fierce. “Korean strategic investors are very active, and their level of deal execution keeps rising,” he observed.
However, Schmitz pointed out that “the constraint is not competition.” “Competitive intensity in Japan, Korea and Australia remains relatively lower than in the US or Europe, even for smaller companies. For me, the main constraint is access to good managers.”
While global LPs have decided Japan, Korea and Australia belong at the core of their Asia allocations, the challenge lies in entering the funds that matter.
Japan is the clearest example. Western LPs have been moving capital from China towards Japan, Australia and Korea. Domestic institutions are raising their home allocations too. For large asset pools, a shift of a percentage point or two is a lot of money. It is all heading for a small group of managers who have returned capital, and the best of them are heavily oversubscribed.
“You have a reasonable number of good managers, but they are oversubscribed,” Schmitz said. “There is big and growing demand from local LPs that want to put more money to work. At the same time, a lot of Western LPs want to put money to work in Japan.”
The return environment is also becoming less forgiving. The easy years of lower mid-market investing in Japan — cheap entry prices, cheap leverage and willing strategic buyers at exit — are fading. Competition is pushing valuations higher, while rates and more cautious lenders have made financing less supportive. For foreign investors, currency adds another layer of risk.
“Because of competition, entry prices are gradually increasing,” said Kobayashi. “Even in Japan, we are having higher interest rates, and banks are a bit cautious.” On currency, he added: “The Japanese yen is very weak now, and we are not sure whether it will get stronger in the near future.”
“I expect overall returns to be lower in the future, and there will probably be more difference between good managers and okay managers,” Kobayashi said. “But there are not so many good GPs in the market. Manager selection is getting more difficult.”
Kuwaki said cultural considerations can make owners in some remote prefectures wary of dealing with foreign investors. “Founders really care about how the private equity firm is going to treat the employees, even after he’s gone.”
At the lower end of these markets, deals are won locally. Owners, especially outside the big cities, want a buyer who speaks their language, understands their employees and will still be there after the founder leaves.
That can make it more difficult for pan-regional funds and geographically distant LPs to establish relationships in local markets. For an LP in London or New York, building a relationship with a manager in Tokyo or Melbourne can require regular calls across time zones as well as in-person meetings.
“It’s easier to be in New York and invest in London,” Schmitz said. “If you want to invest in a Melbourne- or Tokyo-based GP, you need to adapt to taking calls at odd times. It is what it is.”
Against that backdrop, Kobayashi’s own answer has been to spend the past five or six years backing emerging managers, including younger talent who can be aggressive, “but in a good way”.