As China’s private equity (PE) market stabilises after a turbulent few years, global investors are recalibrating their playbooks to selectively capture opportunities in a maturing market defined by discipline and distinct dual-currency capital dynamics.
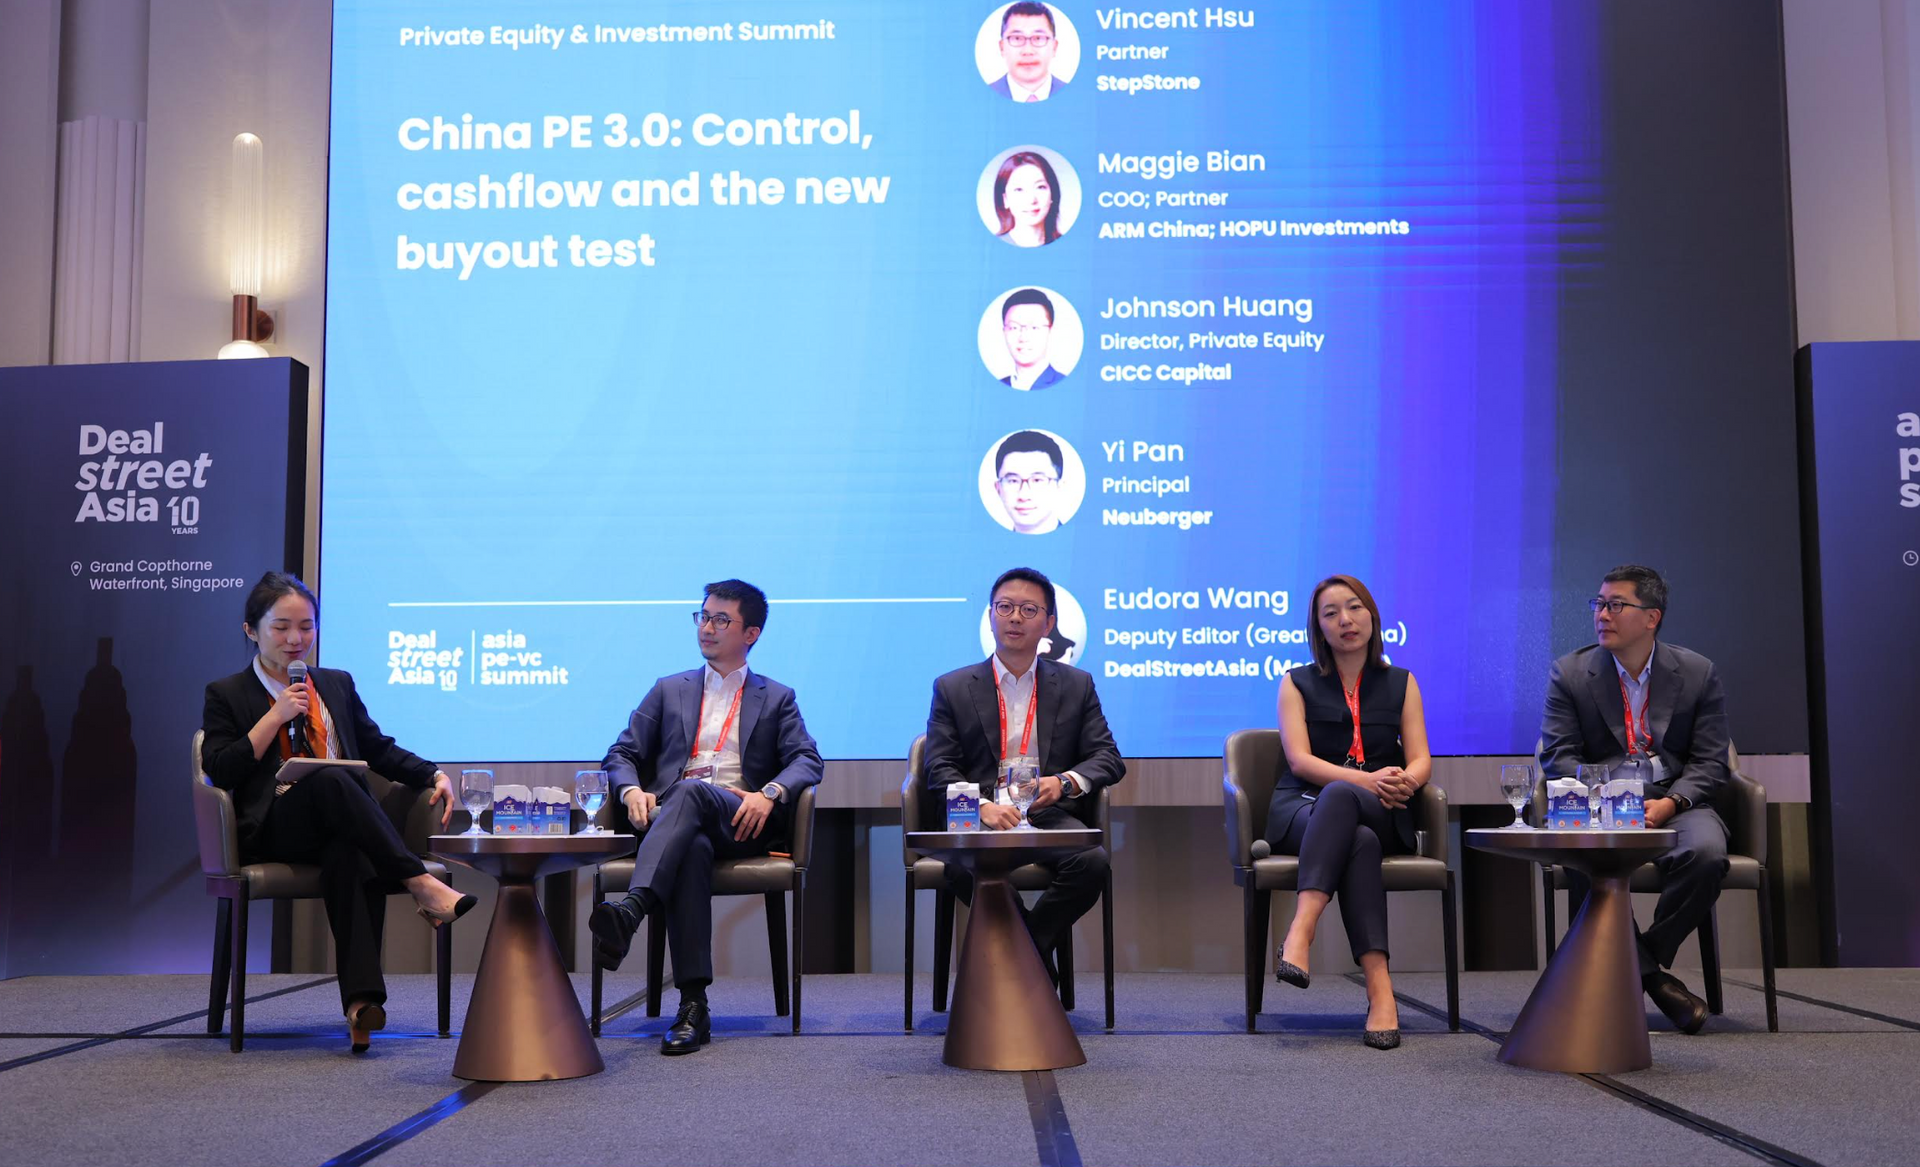
Speaking at a panel titled “China PE 3.0: Control, cashflow and the new buyout test” during DealStreetAsia’s Asia PE-VC Summit 2026 in Singapore, China-focused global and regional investors mapped out some high-conviction opportunities in China’s evolving PE landscape.
Disciplined PE recovery meets persistent investor caution
Dealmaking in China’s PE market staged a strong comeback in the first half of 2026, with deal volume almost tripling to 1,209 and deal value surging 86% year-on-year (YoY) to $94.8 billion. High tech, industrials and healthcare were the top three sectors for PE investors in this market, reflecting a close alignment with national policy priorities, according to a PwC report released in August.
China-focused PE fundraising in US dollars is also stabilising, with a number of sizeable funds returning to the market for fundraising this year following a slow deployment period post-2022, said Vincent Hsu, a partner at StepStone.
“One of the brighter spots is definitely on the venture side,” said Hsu, noting that a pullback from US assets by global investors to reduce over-concentration in the US and seek higher growth potential elsewhere has offered “a great opportunity” for non-US LPs to invest in China’s early-stage venture capital (VC) market.
As funds raised during the 2021-22 market peaks reach full deployment, a group of China-focused GPs are coming back for new fundraising campaigns. Private markets placement firm Asante Capital, cited in an August 2 Financial Times story, recorded active fundraising efforts seeking an estimated $35 billion for at least 60 new China-focused USD funds, including about 40 VC funds.
The half-year GP fundraising results showcased the selective nature of returning global LPs. While RMB capital maintained its dominance, LP commitments to China-focused, foreign-currency funds—predominantly in US dollars—surged 122.5% YoY to $6.7 billion in H1. But LP allocations in US dollars remained highly selective, with the number of newly closed USD funds falling 9.5% to just 19, according to Chinese private markets researcher Zero2IPO Research.
“We are seeing more deals, but that’s not driven by GPs raising more money. That in part gives me a little bit of comfort that this [China PE] recovery is in a way disciplined because it is not liquidity-driven,” said Yi Pan, a principal at Neuberger.
Yi, who leads Neuberger’s PE investments in Greater China across both fund investments and co-investments, observed that Chinese GPs have altered their underwriting models by largely eliminating multiple expansion as a baseline return driver. Instead, managers are pricing in valuation compression as a baseline underwriting assumption even when acquiring assets at discounted entry multiples.
As the country’s economic momentum slows, panellists highlighted that its PE market has shifted from macro-driven expansion to an era defined by disciplined fundraising, selective investing, operational value creation and structured exits.
Within China, domestic LPs are also enforcing non-negotiable fund performance criteria in their GP selection process. Johnson Huang, a director at CICC Capital’s PE department, revealed that the firm’s investment committee now applies “a strict hard gate for DPI (Distributions to Paid-In Capital)”: To qualify for an LP cheque from CICC Capital, one of the key prerequisites is that prospective GPs must have at least one prior fund achieving 1.0x DPI or higher.
The adoption of more disciplined metrics in China’s PE market comes as global investor sentiment towards China is slowly shifting from outright avoidance to cautious, selective re-engagement. But structural constraints remain.
From an LP perspective, global investors remain cautious about China for a few reasons, said StepStone’s Hsu. “Part of that is geopolitical, but another part is their existing China portfolios are underperforming. Until that somehow gets resolved—whether through exits that come back as distributions or simply an uptick in valuations—the issues remain.”
Two currencies, two playbooks
China’s PE market has made a comeback, but it is a different market from the one that global investors left behind amid a bifurcation between RMB and USD strategies.
In H1, RMB-denominated equity investment funds commanded well over 90% of total LP commitments in this market, according to China’s Zero2IPO Research. In terms of dealmaking, capital deployment in its private markets was relatively more balanced: RMB deals accounted for nearly 71% of total investment value, while foreign-currency deals, largely denominated in US dollars, contributed to the remaining 29%.
This dual-currency dynamics have created distinct investment and exit pathways. “The delineation is less remarkable for control buyouts. But in venture and growth, it is more sector-driven, with certain sectors more susceptible to geopolitical considerations,” said Neuberger’s Pan.
“A lot of the companies, because of regulatory or exit considerations, are taking more RMB instead of USD.”
Meanwhile, several global and regional investors are gradually expanding into the RMB market, raising RMB funds to operate under a dual-currency structure, building onshore entities or converting foreign capital into Chinese yuan at the fund level through the Qualified Foreign Limited Partnership (QFLP) regime to explore onshore opportunities and preserve deployment flexibility, said Pan. “The overarching message is there are different ways to explore both the USD and RMB markets.”
In areas where underwriting standards, fund terms and exit routes between RMB and USD diverge, Huang summarised CICC Capital’s core operational difference: “For the RMB market, we’re getting closer to the government. For USD, we’re getting close to the industry.”
Given CICC Capital’s parentage being the partially state-owned Chinese financial services group CICC, his PE team on the RMB side collaborates closely with government entities across the full lifecycle from startup incubation and early-stage VC to growth-stage PE and public listings.
As an example, Huang cited a CICC Capital-managed, RMB VC fund-of-funds (FOF) seeded with 20 billion yuan ($3 billion) from the Beijing Municipal People’s Government, which has committed to 78 Chinese GPs to date.
He also chairs a 1.6-billion-yuan ($238.7 billion) non-profit foundation backed by donors such as Xiaomi Corp, Tencent Holdings and ByteDance. Focused on healthcare innovations, the foundation has effectively “monopolised” deal sourcing from top hospitals in Beijing, according to Huang.
In comparison, on the USD side, where CICC Capital has built joint vehicles like the $1-billion AstraZeneca-CICC Healthcare Investment Fund in collaboration with AstraZeneca and is now partnering with a German biopharma company on another USD fund, the strategy is being “closer to industrial players,” said Huang.
Citing official data from China’s National Medical Products Administration, Huang said that China’s booming innovative drug business development (BD) out-licensing market reaching a record high of about $110 billion in H1, already 80% of 2025’s full-year total, is evidence that industrial partnerships have become critical for exits.
With overseas listings via traditional Variable Interest Entity (VIE) structures virtually halted, Huang said “we need to find new exit methods,” pointing to out-licensing deals as a vital pathway for healthcare assets in China.
Furthermore, this currency split has created contrasting dynamics within the secondary market. Hsu, who covers StepStone’s PE primaries, secondaries and co-investments in Asia, said that GP-led USD continuation vehicles (CVs) are increasing in China driven by quality assets and certain LPs seeking liquidity. But LP-led USD secondaries remain scarce due to persistently wide bid-ask spreads.
On the RMB side, the dynamic is different.
“You have a lot of RMB capital invested in funds that tend to be more tech-related, and you have very motivated sellers who are very different from USD sellers,” said Hsu.
Many of these sellers are willing to sell at meaningful discounts after holding the assets for a few years, prioritising capital recycling over return maximisation. “If you want more access to high-tech assets, the RMB secondary market is probably the better way to go,” he said.
PE battles talent shortage as control opportunities rise
In a maturing PE market where control buyout opportunities are also emerging, the operational distinction between USD and RMB capital is less pronounced.
While China’s private markets remain mostly venture- and growth-driven, investors expect more control buyout opportunities in this market after several big-ticket transactions involving MNCs transitioning their China operations to local ownership to combat growing domestic competition and lingering geopolitical risks.
However, executing cross-border control deals and creating value post-transaction still face a major constraint: a severe shortage of experienced operational PE talent in China and across Asia.
Having retuned $1.2 billion to LPs throughout 2025, HOPU Investments partner Maggie Bian detailed how the Asia-focused, control-oriented alternative asset management firm addresses this talent deficit through a three-part strategy.
Bian said that the firm has built a network of over 10 operating advisors, including experienced CEOs, CFOs and CMOs across various sectors with both domestic market expertise and international expansion know-how to support cross-border value creation. While HOPU maintains its connections with a broader pool of top Asian executives for potential PE-backed leadership roles, it also mandates typically 6-12 months of internal team secondments into portfolio companies to drive hands-on revamps whenever and wherever needed.
“While we’re looking at deals, we’re constantly assessing the talent pool we’re able to tap into. Because without talent, a deal actually cannot happen. The deal itself might make sense, but when we look at the operational levers, that’s where talent really comes into play,” said Bian. “By the time we get the deal done—say, day minus 30—you probably need to have a management team ready to come on board.”
Alongside management transformation, Bian also highlighted three key post-deal, value-creation levers for HOPU, including expanding revenue through new channels and local partnerships, providing cross-border regulatory insights and exploring bolt-on acquisitions.
A prime example is ARM China, which was carved out by a HOPU-led consortium in 2018 from UK-headquartered Arm Holdings for $775 million. Supported by HOPU’s financial and Chinese market network, ARM China pivoted to building a local ecosystem to offer semiconductor architectures tailored to Chinese clients, which tripled its revenue between 2017-2022.
Bian herself stepped in as ARM China’s COO in 2025 to steer its China expansion, noting that ARM China is “on track to deliver one of its highest profits this year.”
Other value-creation strategies, such as helping portfolio companies navigate Asia’s regulatory landscapes and execute bolt-on acquisitions, have driven revenue growth and global expansion for assets including HOPU’s minority-owned French animal health company Ceva Animal Health and regional logistics giant GLP.